
Budget 2026: Lifetime ISA withdrawal fine axed for homes above £450,000 in major MSE win – plus First-Time Buyer ISA launch confirmed


The withdrawal penalty first-time buyers are charged when purchasing homes above the Lifetime ISA's (LISA) current £450,000 property price limit has been AXED as of Thursday 29 October, following the Chancellor John Healey's Budget. The Government has also confirmed that it will go ahead with the launch of the already trailed First-Time Buyer ISA (FTB ISA). We've full info below...
-
Watch Martin explain which is best – the LISA or the new FTB ISA?
-
Listen to Martin answer whether a LISA is still worth it for first-time buyers and retirement.
-
Read on for more details on the FTB ISA and LISA changes, as well as the process if you're planning to use your LISA soon.
Lifetime ISA vs First-Time Buyer ISA – which is best?
Plans to scrap the LISA were first announced in the former Chancellor Rachel Reeves' November 2025 Budget. This is when Ms Reeves also revealed plans to consult on a new ISA for first-time buyers. Further details on the FTB ISA were put forward in June 2026, and now the Government has confirmed it'll take force from April 2029.
Martin compared the two ISAs on ITV's The Martin Lewis Money Show Live on Thursday 29 October. Here's what he said:
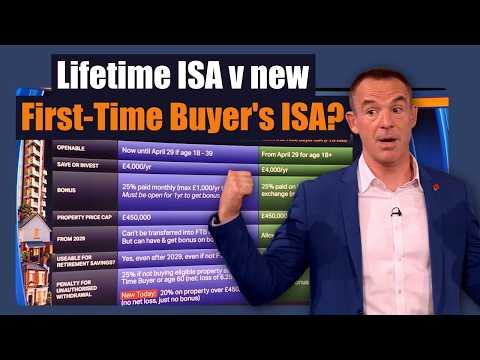

From The Martin Lewis Money Show Live on Thursday 29 October 2026 courtesy of ITV. All rights reserved. Watch the full episode on ITVX.
Read the full video transcript
Martin Lewis: "The Lifetime ISA is the existing live product. You can open it now up until April 2029. You can open it aged 18 to 39, but it carries on once you've opened it. So once you have it, it's open. But it's all about opening it there.
"The new First-Time Buyer ISA is from April 2029 for age 18+.
"Both allow you to put £4,000 a year in. Both give you a 25% bonus. So in simple numbers; £4,000 is £1,000 free a year.
"On this one [LISA], the bonus is paid every month and then you get interest on top, up to a maximum £1,000 a year bonus until you're age 50.
"On this one [FTB ISA], the 25% is paid on the total in the account on exchange. That includes the interest that you've already earned.
"Interestingly, until yesterday [Wednesday 28 October], they weren't going to include interest. So this actually has been quite a good increase for what people are going to get. Maximum £20,000 bonus there [FTB ISA], technically a maximum of £32,000 bonus there [LISA], if you open it at 18 and kept putting in until 50. But you want to buy a house, so why would you do that?
"Worth noting on this one [LISA]. It must be open for a year before you can get the bonus. So my rule for any 18- to 39-year-old who does not have a Lifetime ISA: put a pound in. If you're a first-time buyer, it means the clock is ticking.
"If you're not a first-time buyer and you've already bought a house, why would you open it? Well, unlike the First-Time Buyer ISA, on the Lifetime ISA, you can use it for retirement savings. And while for most people, it's not as good as a pension – I mean, it's only really competitive if you are a self-employed basic-rate taxpayer – you don't know your future status.
"And if you put a pound in now and open it now. Well, you won't be able to after April 2029, but if you've got the facility open, then maybe in 10 to 15 years' time you'll go, oh, actually, that is a good vehicle for me, for my retirement savings.
"For the sake of a quid, you're just buying yourself a facility. I'm not saying put any more in. I'm saying put a quid in, so that you've got one of these.
"Property price cap, £450,000 on both of those. I know many people have been campaigning that hasn't gone up since it was launched in 2017. It's not going up at the moment.
"It's going to get interesting now. Follow me here for a second... When this starts [FTB ISA], you will not be able to move Lifetime ISA money into the First-Time Buyer ISA. But the rules surprisingly say you can have both and you can get the first-time buyer bonus on both. So you could actually double up.
"And then just to complicate it, the predecessor to the Lifetime ISA is the Help to Buy ISA. You will be able to transfer your Help to Buy ISA into the First-Time Buyer's ISA. I know there's a lot of different ISAs going on here.
"So, where do we go next? We've talked about retirement savings and just worth noting even after April 2029, you will still, they're saying it will still work in exactly the same way as long as you've got one open.
"Now we come to one of the more complicated changes. This is how it works, right. Yesterday [Wednesday 28 October], if I was standing here yesterday explaining the Lifetime ISA, what I would have said is if you withdraw money other than for buying a first-time property under £450,000, or once you're age 60 – so using it for retirement savings, then you would have a 25% penalty.
"So, remember you got a 25% boost and a 25% penalty. The penalty is on a bigger amount. What that actually worked out is you would have to pay the Government back 6.75% [Martin note: "Oops, just noticed when I said '6.75%' fine that was a slip. I thought I had, and should have, said '6.25%'. It makes no difference but just to be accurate."] of the money you put in.
"So if you put £10,000 in, you'll get about £9,400 out. So you effectively were paying the Government a fine. And the thing that was most aggravating for me is you would have to pay that fine if you're buying a property above £450,000. So you started saving in 2017. You've finally got your money together, you've been priced out, and now you can't get your money out without paying a fine.
"That's gone. And in fact, it's gone today [Thursday 29 October]. It now does not exist. It's a very specific exemption. If you take your money out to buy a property over £450,000, the penalty is now 20%, which sounds complicated, but what that effectively means – 25% on top, 20% off. You get back the money you put in, plus the interest. You just don't get the bonus.
"So at least you're not losing anything. Which is exactly the same as if you take the money out of there [FTB ISA]. So because there's no bonus, but you don't get a penalty.
"So to answer, Martin [viewer with a question], if your daughter is definitely going to buy a property, I no longer have to caveat that by saying 'a property under £450,000'. I would be opening a Lifetime ISA. Especially as the fact is that you can have both. If she's not definitely going to be buying a property, then you have to be slightly careful because that 25% penalty would still apply."
So is the LISA is still worth it for first-time buyers and retirement?
If you've got a LISA, or you don't but you're aged under 40, listen to Martin's podcast...
Mini Question Time: Is a LISA still worth it for first time buyers and retirement, now it's being replaced?
The Martin Lewis Podcast: Released 2 November 2026
Listen to this edition of the The Martin Lewis Podcast for free on BBC Sounds | Apple Podcasts | Spotify or most other places that you get podcasts from (and why not subscribe while you're there?).
Martin Lewis answers a listener's question about Lifetime ISAs (LISAs), explaining how they were affected by the Chancellor's Budget announcements. He breaks down how LISAs work, whether the Government announcement affects first-time buyers or savers, and the key rules, bonuses, and withdrawal penalties to be aware of.
Martin also looks at whether a LISA can be used as an alternative to a pension, how the Government bonus works, and the key advantages and drawbacks of saving for retirement this way.
Lifetime ISA win for MSE
LISAs are designed to help people aged 18 to 39 buy their first home or, much less popularly, to save for retirement. Savers get a 25% Government boost when they use the funds to buy a qualifying first home. They're a powerful product – still beneficial to many – which can give a huge boost to first-time buyers' savings.
But the scheme's £450,000 house price limit has remained frozen since it launched in 2017, despite house prices rising significantly since then. This has left some first-time buyers unable to find a suitable property under the limit, and savers buying a home that no longer qualifies are then effectively charged a 6.25% penalty on their own money when withdrawing – something we've been campaigning to fix since January 2023.
The Government has now confirmed that the withdrawal penalty on the LISA has now been axed for those buying homes above the scheme's limit from 29 October 2026 onwards. In practice, this will see the withdrawal charge reduced from 25% to 20% in this scenario.
It means savers using their LISA to buy homes above the scheme's £450,000 limit will lose the Government's bonus, plus any growth or interest earned from just the bonus. But they won't lose any of their own savings or any growth or interest earned on their own money.
Example 1:
Helen subscribes £4,000 to a LISA and a £1,000 government bonus is paid.
Helen earns 5% annual interest/growth on the total, at £250. This takes the total balance to £5,250.
Helen withdraws the funds to purchase a house over £450,000.
A 20% charge on the withdrawal of £5,250 means:
- The Government recoups £1,050 – the £1,000 government bonus paid and £50 for 5% interest/growth earned on this.
- Helen gets back £4,200 – £4,000 subscribed and £200 for 5% interest/growth earned on this.
Example 2:
Sally subscribes £4,000 to a LISA and a £1,000 government bonus is paid.
After investing, this goes down by 5% – £250. This takes the total balance to £4,750.
Sally withdraws the funds to purchase a house over £450,000.
A 20% charge on the withdrawal of £4,750 means:
- The Government recoups £950 – £50 less than the original bonus.
- Sally gets back £3,800 – £200 less than Sally put in.
Martin Lewis: 'This will be a great relief to many young people'
Commenting on the announcement, Martin said:
NEWS: Delighted after years of fighting for it that the Lifetime ISA (LISA) penalty for those buying a house of £450,000-plus will be reduced from 25% to 20%. In practice (as you got a 25% bonus when putting money in) this means while you won't get the bonus, you'll get back what you put in, plus interest. I've long suggested this and I am pleased the Chancellor listened.
It means there's no risk to putting money in a LISA if you're definitely going to buy a house. As if you're priced out, and have to go above the threshold, you still get your savings and the interest, you just don't get the extra.
This will be a great relief to many young people.
The Chancellor has confirmed too that the First Time Buyer ISA replacement will go ahead, but that will take a few years, I suspect. The LISA will remain for now, and should still be viable even once it's closed to new starters.
Buying a home with a LISA? Here's how it'll work in practice
In practice, if you're using your LISA to buy your first home, you shouldn't see any change to the buying process. You should continue to follow the existing house-purchase withdrawal process through your conveyancer.
This includes providing a declaration – likely through a form – to your conveyancer that, among other things, you're a first-time buyer, as well as the full address and purchase price of the property. If you're purchasing a home with another LISA holder, you must both make your own separate declarations to your conveyancer/s.
Your conveyancer will then pass this information on to your LISA provider, which will then deduct the reduced 20% withdrawal charge and release your LISA funds to your conveyancer within 30 days of receipt of the declaration.
Note: This applies to eligible withdrawals made on or after 29 October 2026. It does not apply retrospectively.
If you withdraw money for any reason other than buying a home (or at retirement), the charge for this will remain at 25%.
First-Time Buyer ISAs – a quick summary
-
The scheme will be available from April 2029.
-
You'll be able to save up to £4,000 a year – the same as with LISAs.
-
You'll earn a 25% Government bonus up to a maximum bonus of £20,000. This is over the life of the product. With LISAs, you earn a 25% bonus of up to £1,000 a year, up to a maximum of £33,000.
-
The property price cap will be £450,000. The same as with LISAs.
-
The bonus will be calculated based on the final balance in your ISA at the point you use it to buy a qualifying home. This WILL include any interest or investment growth accrued in the ISA.
This is different to what was originally proposed earlier this year, when the previous Government planned for the bonus to only apply to net subscriptions (subscriptions minus any withdrawals made before the bonus is claimed).
For example, under the previous plans, someone who had saved £10,000, which had grown to £15,000, who then withdrew £7,000, would only be able to get the bonus on £3,000. Under the new rules, the bonus would be payable on £8,000 instead.
This is also different to LISAs, where the bonus is paid monthly and interest can be earned on top of it. However, the new system means there's now no need for any withdrawal charge. -
There will be no upper age limit to open it. With LISAs you must make your first payment before you turn 40.
-
You can't transfer between FTB ISAs and LISAs, but both products can be used towards the same purchase.
-
Existing LISA holders will be able to continue contributing to and using their accounts.
MSE's Budget 2026 coverage
Check out all of our other MSE News stories following the Chancellor's announcements:
Full round-up of the key measures, including MoneySavingExpert.com (MSE) founder Martin Lewis' video analysis of what they mean for you.
The planned cash ISA limit cut for under-65s WON'T go ahead. Also, plans for a 'starter investment ISA' (something Martin's argued for) have been announced. We explain what's happening.
Millions of households in Council Tax bands A-D will get a £100 payment next year to help with energy costs. Funding's also being allocated to Northern Ireland, Scotland and Wales for similar schemes.
Gas Standing Charges will FINALLY be scrapped in a move MSE has campaigned on for years. Watch Martin's instant reaction and analysis.
State Pensioners with incomes under £13,037 a year to pay NO Income Tax as new allowance introduced.
New 'Your First Home' homebuying scheme to launch in England. It was first announced in September and now more details have been revealed – we explain how the scheme will work.

Share this guide?


 Latest weekly email


Clever ways to calculate your finances


